Customer Intelligence for Financial Services in the UAE

Insights / Customer Intelligence for Financial Services in the UAE

Customer Intelligence Financial Services UAE

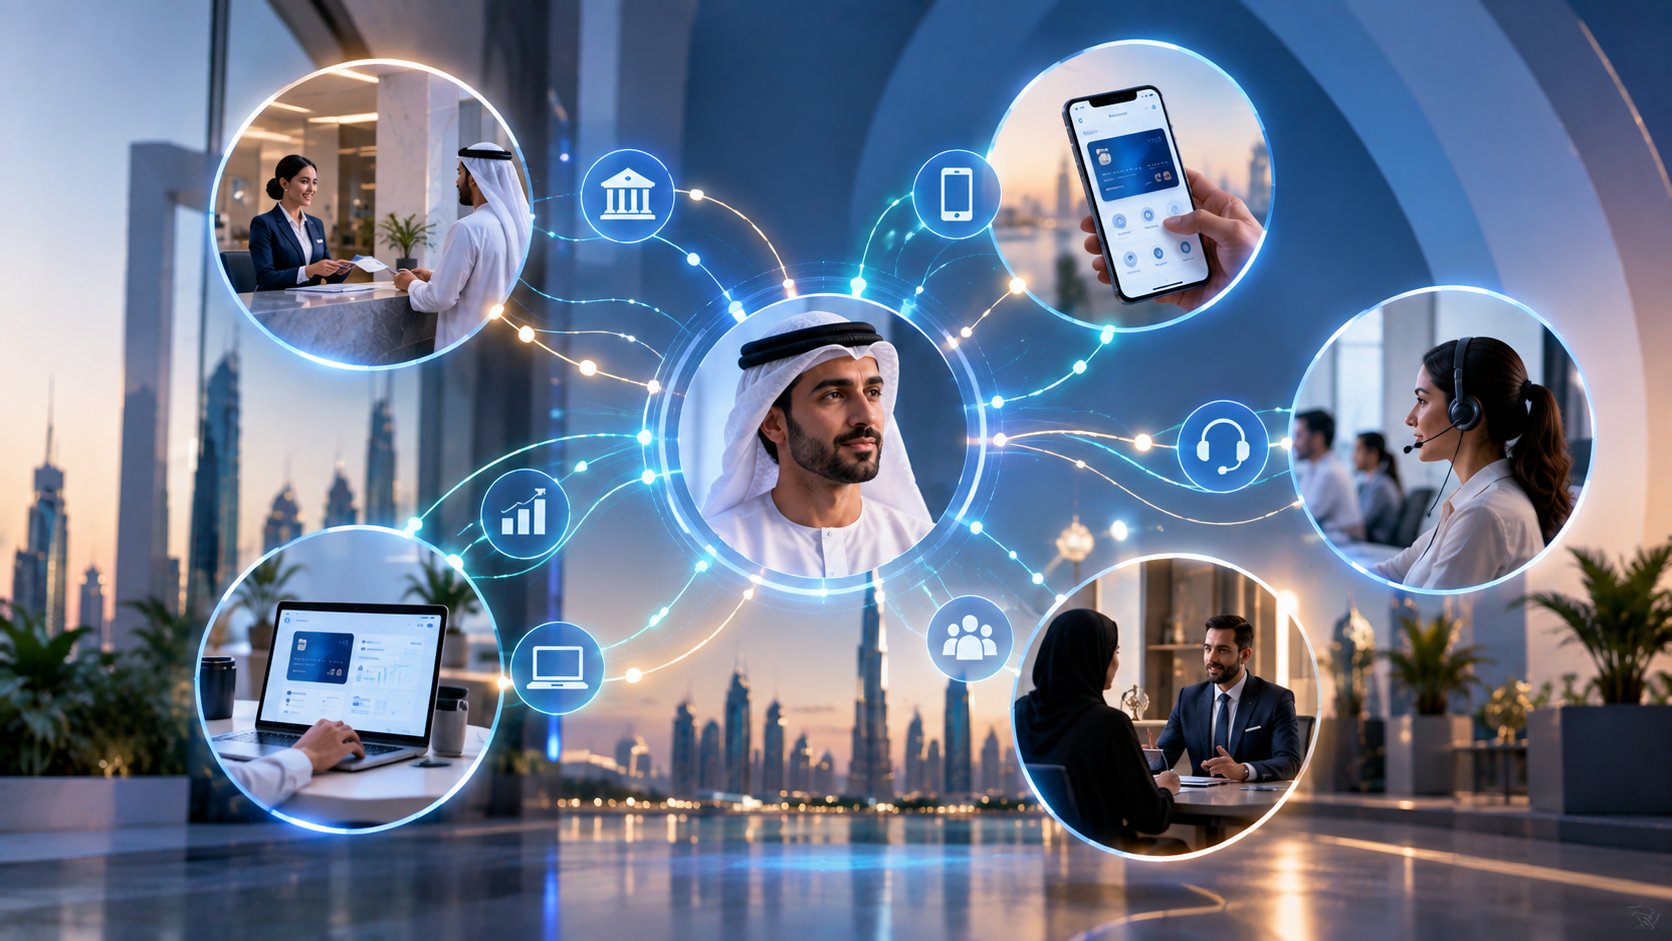
For a UAE bank, insurer or wealth management group operating across multiple branches, products and business lines, customer intelligence depends on how effectively the organisation can connect the information it already holds. A retail banking system may hold account and transaction information, a wealth platform may hold investment data, and an insurance system may hold policies and claims — while interactions sit across contact centres, digital channels and relationship-management platforms.

This is becoming more important as institutions expand their use of AI. Deloitte’s 2026 Banking and Capital Markets Outlook reports that more than 90% of banking data users surveyed said the data they need is often unavailable or takes too long to retrieve, while 81% identified data quality as a top challenge. For UAE financial institutions, customer intelligence starts with a strong data foundation and extends into how that intelligence supports service, engagement, risk management and relationship growth.

What Unified Customer Intelligence Means

Unified customer intelligence brings relevant information from connected business systems into a continuously updated customer profile, so authorised teams can see a connected view of the relationship rather than one business-line’s slice of it. The process involves three capabilities working together:

  • Data capture: bringing relevant information from connected systems into one environment.
  • Data unification: resolving and associating records so information relating to the same customer contributes to one current profile.
  • Intelligence and decisioning: applying analytics, scoring and business logic to that connected profile to identify opportunities, risks or appropriate next actions.

Unifying customer data creates the foundation. Intelligence applied to that foundation determines how the organisation can put the information to work.

Enterprise Use Cases Across UAE Financial Services

  • Retail banking: a customer contacting the bank about a card issue may also hold a mortgage, savings products and investment services. A connected view lets a service professional handle the immediate request with the broader relationship in sight.
  • Insurance: customer intelligence brings policy, claims and interaction information into one relationship view, so a claims professional works with relevant history while a relationship team sees the customer’s wider engagement.
  • Wealth management: understanding a client extends beyond a single portfolio. A connected environment brings together portfolio information, service interactions and product relationships for stronger client conversations.
  • Islamic banking: a customer holding Murabaha financing, savings products and Takaful arrangements can be represented as one relationship across connected systems, giving teams a complete basis for service and product engagement.

Why Cross-Channel Intelligence Matters

Financial relationships increasingly span branches, mobile apps, websites, contact centres and relationship managers, and each interaction creates a signal worth connecting rather than evaluating in isolation. This is where Instant Cross-Channel Attribution and Intent Mapping becomes relevant: associating behavioural and engagement signals with the broader customer relationship as a customer moves from a digital interaction to a service conversation to a product discussion, rather than treating each as an isolated event. The result supports more relevant engagement and gives teams a stronger read on where the relationship may be heading.

Governance Is Part of the Foundation, Not an Add-On

The UAE’s Federal Decree-Law No. 45 of 2021 on the Protection of Personal Data establishes a framework for personal-data processing, confidentiality and data-management responsibility. The UAE’s official Charter for the Development and Use of AI adds further emphasis on data privacy, transparency, human oversight and accountability in how AI is developed and used. For financial institutions, this makes governance integral to customer intelligence — who can access specific customer information, how AI-supported decisions are governed, and where human oversight remains appropriate all need to be answered as part of the same design, not bolted on afterward.

Customer Intelligence Financial Services in UAE

Where Worktual's AI Advanced Intelligence Platform Fits

Worktual‘s AI Advanced Intelligence Platform is built around Enterprise Data Sovereignty and Intelligence — capturing and unifying relevant customer information from connected systems into a Single Source of Living Truth that stays current as new interactions occur, rather than depending on periodic reconciliation.

On top of that unified profile, the platform applies Predictive Enterprise Value Modeling to identify patterns that matter operationally: changes in engagement, cross-product opportunities, service issues requiring attention, and signals that call for follow-up from a relationship or service team. Instant Cross-Channel Attribution and Intent Mapping connects those signals across digital, branch and assisted channels, while Expansion and Upsell Velocity turns relevant patterns into next-best-action guidance for relationship and service teams.

For CTOs and CIOs, the emphasis is on a connected intelligence environment with enterprise integration, governance and control built in from the start. For business and transformation leaders, the opportunity is turning customer information into a continuously useful enterprise asset — across retail banking, wealth management and insurance — that supports better service and stronger relationship understanding.

Conclusion

For UAE financial institutions, customer intelligence is becoming an enterprise capability rather than a single-system function. Banks, insurers and wealth managers already hold valuable customer information across products, channels and business lines; connecting that information — with the governance financial services regulation expects — creates a stronger foundation for responsive customer experiences and long-term relationship value.

Frequently Asked Questions

1. What is unified customer intelligence in financial services?

It’s the practice of bringing relevant customer information from connected systems — banking, insurance, wealth, service and digital channels — into one continuously updated profile, so authorised teams can see the full relationship rather than one system’s slice of it.

2. Why does this matter specifically for UAE financial institutions right now?

Deloitte’s 2026 Banking and Capital Markets Outlook found more than 90% of banking data users say needed data is often unavailable or slow to retrieve, and 81% cite data quality as a top challenge — gaps that become more costly as institutions expand their use of AI.

3. How is customer data governed under UAE regulation?

The UAE’s Federal Decree-Law No. 45 of 2021 sets the framework for personal-data processing and confidentiality, while the UAE’s Charter for the Development and Use of AI adds requirements around transparency, human oversight and accountability for AI-supported decisions.

4. Which financial services functions benefit most from unified customer intelligence?

Retail banking, insurance, wealth management and Islamic banking all benefit, since each involves customers holding multiple products or relationships that are otherwise visible only in separate, disconnected systems.

5. What is cross-channel intelligence, and why does it matter?

It’s the ability to connect a customer’s behaviour across branches, apps, websites and contact centres into one relationship view, rather than treating each channel’s interactions as isolated events — supporting more relevant engagement and better-timed follow-up.

6. How does Worktual’s AI Advanced Intelligence Platform support this?

It unifies customer information into a continuously current profile, applies intelligence to surface patterns that matter operationally, and connects signals across channels — all within governance and access controls suited to financial services.

Related Posts

AI Native vs AI Assisted CRM UAE

AI-Native vs. AI-Assisted CRM: What Actually Matters in the UAE

Customer service expectations have changed significantly across digital channels. Customers now expect immediate responses, accurate resolutions, and seamless support experiences across chat, email, voice, messaging apps, and self-service platforms. At the same time, enterprises are handling growing ticket volumes while trying to reduce operational costs and improve service efficiency. Traditional ticket management systems often struggle because support operations remain dependent on manual workflows, disconnected tools, and repetitive processes that slow down issue resolution.

PDPL Ready What UAE Enterprises Should Require

“PDPL-Ready”: What UAE Enterprises Should Actually Require From That Claim

Customer service expectations have changed significantly across digital channels. Customers now expect immediate responses, accurate resolutions, and seamless support experiences across chat, email, voice, messaging apps, and self-service platforms. At the same time, enterprises are handling growing ticket volumes while trying to reduce operational costs and improve service efficiency. Traditional ticket management systems often struggle because support operations remain dependent on manual workflows, disconnected tools, and repetitive processes that slow down issue resolution.

Dubai Health Insurance Claims Deadline

Dubai’s New Health Insurance Claims Deadline

Customer service expectations have changed significantly across digital channels. Customers now expect immediate responses, accurate resolutions, and seamless support experiences across chat, email, voice, messaging apps, and self-service platforms. At the same time, enterprises are handling growing ticket volumes while trying to reduce operational costs and improve service efficiency. Traditional ticket management systems often struggle because support operations remain dependent on manual workflows, disconnected tools, and repetitive processes that slow down issue resolution.